He Ditched Nvidia and Raised $350M. Here's the Playbook.
TensorWave turned down the market leader and hit a $1.55B valuation. Three tactical moves any founder can borrow.
A data center startup that refuses to touch the world's dominant AI chip just closed $350 million at a $1.55 billion valuation. Worth a second look.
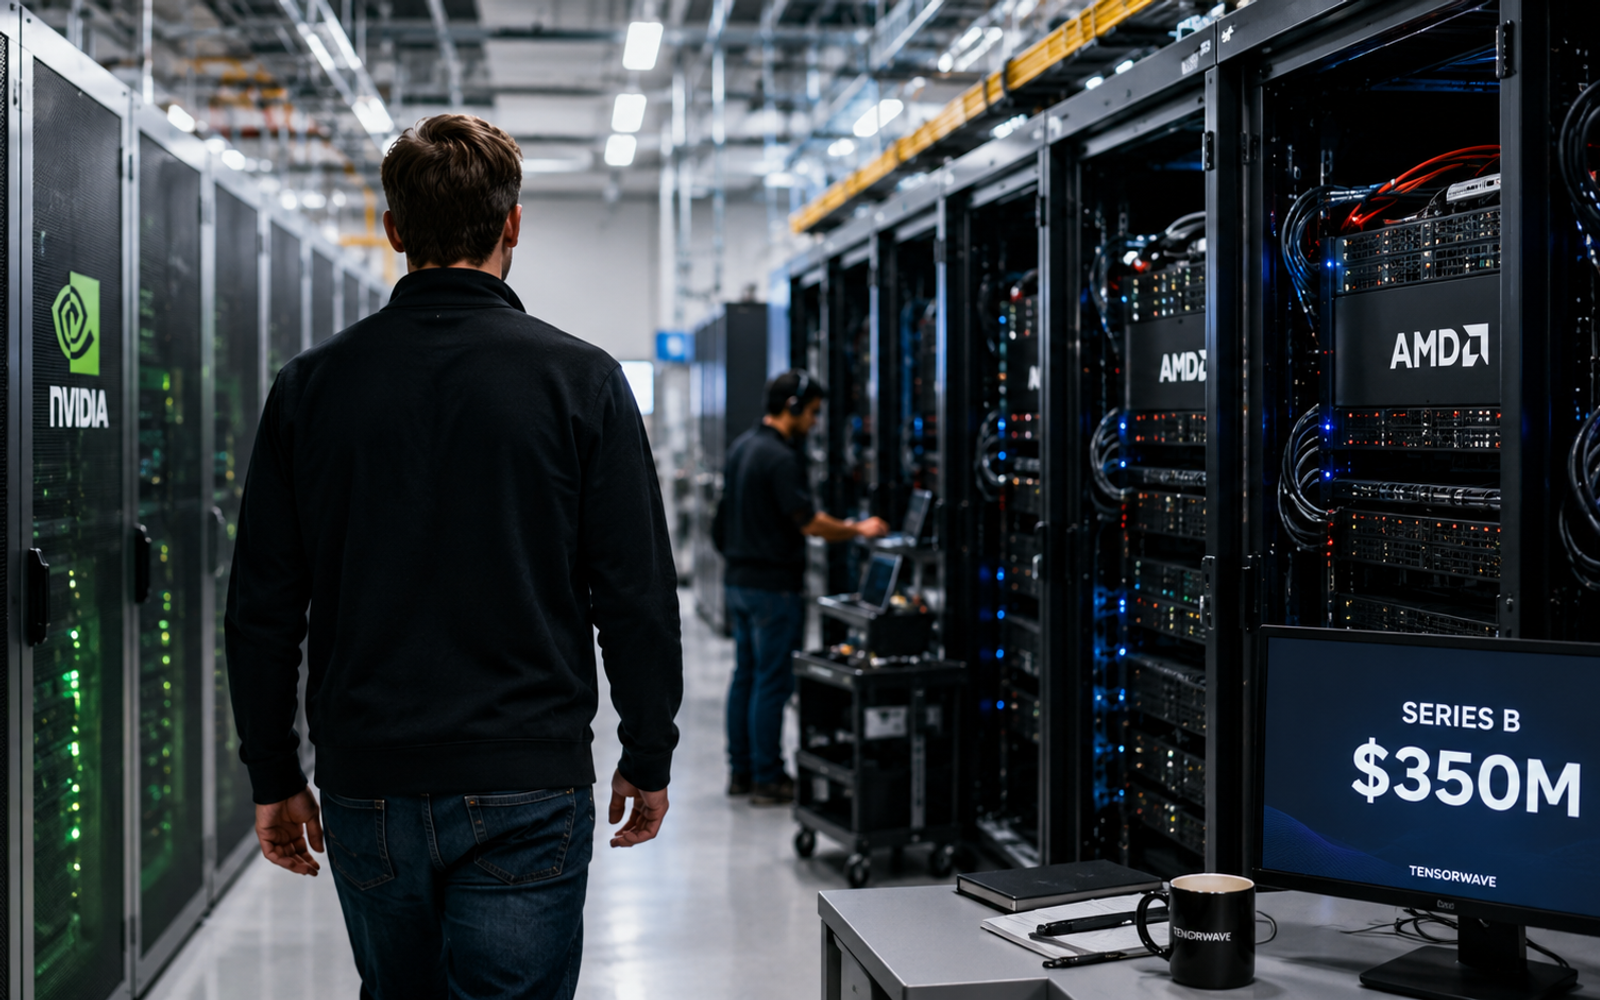
TensorWave was founded in 2023 by Darrick Horton, Piotr Tomasik, and Jeff Tatarchuk to build AI infrastructure exclusively on AMD hardware. No Nvidia. Not one H100 or B200 anywhere in the fleet. The Series B closed in June 2026, led by AMD Ventures and hedge fund Magnetar Capital, with Maverick Silicon, Nexus Venture Partners, and Western Frontier also writing checks. The Wall Street Journal reported that this new valuation is nearly four times what the company was worth after its Series A in May 2025, which came in around $400 million.
Call it an anti-Nvidia bet if you want. The market seems to think it's just a necessary one.
The Bet That Broke Open the GPU Bottleneck
Most people talking about the AI infrastructure crunch are still describing it as a shortage. It's really a monopoly problem. Nvidia controls somewhere north of 80% of the AI accelerator market, which means it also controls pricing and who gets shipped chips first. If you're a startup building training clusters and you're not already a preferred customer, you wait. And waiting kills speed.
TensorWave decided not to wait. Instead of fighting Nvidia's allocation queue for scraps, the company committed fully to AMD's Instinct line. It now runs 8,192 AMD MI325X GPUs across its North American clusters, by some measures the largest AMD-based AI training fleet on the continent, and it's rolling out the next-generation MI355X chips across several new data center regions.
Customers like Fireworks AI and Luma AI are already running production workloads on that infrastructure. TensorWave also brought in networking firm Credo to shore up reliability across the clusters, which matters more than it sounds. A fleet of 8,000 GPUs is only as good as the network stitching it together. One bad cable or misrouted switch and you've got a very expensive paperweight.
The underlying decision here isn't really about chips. It's that TensorWave treated its dominant supplier as a liability instead of an asset, and built a company around the alternative.
The AMD Play Isn't the Only Play
TensorWave's story can make it look like the lesson is "pick AMD." It isn't. The real lesson is about what it costs to stay locked into a single supply chain, and different companies are answering that question differently right now.
Look at the broader specialized GPU cloud landscape. Emerging infrastructure providers like CoreWeave, Lambda Labs, and Crusoe built multi-billion-dollar valuations by securing massive allocations of Nvidia H100 and B200 systems, accepting strict supply queues and high capital expenditures in exchange for CUDA's established software dominance. In contrast, startups taking the open-silicon path are betting on AMD's ROCm open-source stack, faster procurement cycles, and lower cost-per-token economics.
Both paths are chasing the same exponential demand for AI compute, but they make opposite calls on where the strategic moat lives. One path pays high margins to preserve software compatibility and the incumbent performance lead. The other bets on hardware diversification and a shrinking architectural gap. Which model makes sense depends on whether your competitive advantage is day-one compatibility or operating margin flexibility.
How to Decide Which Supply Chain Bet to Make
A few questions worth running through before locking into any vendor for years:
How much of your margin does the dominant supplier already control? If you're paying premium prices and sitting in an allocation queue while competitors get priority, that's not a moat you're building. It's rent you're paying on someone else's.
Can the alternative get you most of the performance for a lot less money? AMD's MI325X and MI355X chips don't win every benchmark against Nvidia. But for a lot of inference and training workloads, they're close enough that lower cost and better availability tip the math in their favor.
What happens if your supplier decides to become your competitor? Nobody asks this one, and they should. Nvidia isn't just selling chips anymore. It builds full data center systems, networking gear, and software. A supplier that can also become your rival is a relationship with a shelf life you can't see coming.
The Liquidity Drain Nobody's Watching
The flip side of TensorWave's $350 million round is what it says about the cost of playing this game at all. Between its Series A in May 2025 and this raise, the company burned through roughly $100 million. Power, cooling, real estate, networking, the chips themselves, none of that runs cheap, and none of it runs on a bootstrap budget.
That should worry founders well outside AI infrastructure too, because the fundraising bar keeps climbing. A $100 million Series A used to be a rocket-company number. Now it's closer to standard for anyone building AI hardware at scale.
For founders building without sovereign-scale balance sheets or mega-fund venture backing, the playbook looks different by necessity. You do not need to raise $350 million or buy thousands of physical accelerator cards to build a defensible company in the AI surge. Massive hardware buildouts create an equally massive downstream service economy: cluster orchestration, dynamic load balancing, model fine-tuning pipelines, automated observability, and networking optimization. That is where smaller, capital-light software startups find durable, high-margin footing.
The Execution Lesson That Travels
TensorWave did something a lot of founders talk themselves out of: it picked a lane and stuck to it.
The safer-looking option would have been a hybrid build. Some Nvidia racks for customers who insist on it, some AMD racks for everyone else. Investors tend to like that kind of optionality, at least on paper. But optionality has a cost. Supporting two GPU architectures doubles your engineering surface, splits your procurement relationships, and makes your pitch harder to explain in one sentence. TensorWave chose to be known as the AMD cloud, full stop. That clarity is probably what made it easy for AMD Ventures to lead the round, easy for customers to know exactly what they were buying, and easy for the whole story to fit in a headline.
You don't have to agree with the bet to respect the conviction behind it.
What You Can Actually Steal From This Story
Forget the $350 million. Nobody reading this is about to raise that. What's actually transferable are three habits behind the number.
First, turn a constraint into a differentiator. TensorWave couldn't get enough Nvidia allocation, so instead of apologizing for it, they made the absence of Nvidia the whole pitch. A limitation reads very differently once you frame it as a deliberate choice instead of a compromise you're stuck with.
Second, find a partner whose success depends on yours. AMD Ventures didn't just write a check, it needed a credible customer who could prove AMD chips hold up under real production workloads. TensorWave was that proof. When your supplier's win is tied to your win, the leverage in that relationship shifts in your favor.
Third, build for the bottleneck instead of the boom. Everyone wants to sell into the AI wave directly. Fewer people want to fix the unglamorous stuff that makes the wave usable, reliability, networking, uptime. TensorWave went after exactly that. It's less exciting than training a headline-grabbing model, but it's usually where the steadier revenue actually lives.
A data center startup reached a $1.55 billion valuation because it turned a single-vendor bottleneck into a focused, differentiated advantage. The underlying move is universal: pick an underserved position, align with a motivated supplier whose growth depends on your execution, and let that focus dictate your entire technology stack. Your competitor might still be waiting in line for allocation. You don't have to be.
Comments (0)
No comments yet. Be the first to share your thoughts.